


EXECUTIVE SUMMARY
Five findings reveal the ITFM Value Gap
- Organizations may be overestimating ITFM maturity
69% rate their current ITFM maturity at 8 or higher. Yet among these respondents, 55% still have five or more unresolved high-priority needs. Organizations may be treating established tools, processes, and reporting as evidence of maturity even when executive decision support remains unfinished. - AI spend is outrunning governance
Only 4% are highly satisfied with tracking AI usage, benefits, costs, and ROI. As AI investment accelerates, many organizations lack the financial structures needed to govern it as a portfolio and demonstrate its value. - ITFM value increasingly depends on outcomes
90% say determining whether investments delivered promised outcomes is highly important, but only 13% are highly satisfied. Explaining where money went is no longer enough; ITFM must connect investment decisions to the business value they were intended to create. - Leaders expect AI to improve decisions
Variance explanation is the most frequently selected AI capability, chosen by 79% of respondents. Leaders are prioritizing AI that explains change, identifies action, and improves the forward view—not simply AI that produces more output. - Executive decision support remains unfinished
91% say answering unplanned spend questions without exporting data is highly important; only 9% are highly satisfied. The value of ITFM is constrained when trusted answers cannot reach decision-makers in time to influence action.
OPENING PERSPECTIVE
ITFM has made technology spend visible. The next challenge is making it decision-ready
Established capabilities are not the same as an executive-ready practice
For years, the promise of IT Financial Management was to move beyond disconnected spreadsheets, standardize financial data, and make technology costs more transparent. That work remains essential. Without trusted data, consistent definitions, and credible cost models, every higher-order ambition rests on an unstable foundation.
But visibility is no longer the finish line. Senior leaders need to know what changed, why it changed, what it means for the business, which investments are producing value, where spending can move, and what action should follow. They need those answers in time to influence a decision—not after the meeting, forecast cycle, or funding window has passed.
The ITFM Value Gap is the distance between the capabilities an organization has built and the value those capabilities create at the point of decision. It emerges when established data, models, processes, and reporting do not translate into timely answers, better resource allocation, measurable outcomes, and greater confidence in executive decisions.
This distinction helps explain one of the study’s central findings. Most respondents view their current approach as relatively mature and broadly recommendable. Yet almost every respondent identified at least one highly important outcome that current approaches do not strongly satisfy, and more than two-thirds identified five or more.
ITFM maturity must ultimately be measured by the decisions it improves.
RESEARCH PROFILE
A study of leaders accountable for substantial technology budgets
Nicus commissioned a third-party research agency to source and survey 150 senior IT and technology budget leaders across large North American organizations. Every respondent worked at an organization with at least $50 million in annual IT spend and was personally accountable for governing and defending a technology budget to senior leadership, the C-suite, or the board.
The study was designed to understand ITFM value from the perspective of the leaders accountable for technology investment decisions—not primarily the practitioners who operate the function. Every respondent personally governed and defended a technology budget, and 92% held broader IT or technology leadership roles rather than dedicated IT Finance or IT Business Management titles. This intentional sample design helps reveal whether established ITFM capabilities are translating into the decision support senior leaders need.
Leadership seniority: nearly nine in ten respondents are VP level or above
Industry coverage: respondents represent a broad cross-section of private-sector industries
Budget scale: most respondents represent very large IT environments
CHAPTER 1: THE MATURITY PARADOX
Executive Takeaways
Measure maturity by decision value—not capabilities deployed
- Among leaders who rate their ITFM maturity at 8 or higher, 94% still report at least one unresolved high-priority need and 55% report five or more.
- Evaluate maturity by whether ITFM turns trusted data into timely answers, clear trade-offs and better investment decisions—not simply by the tools, models, processes, and reports the organization has established.
Organizations may be overestimating ITFM maturity
Established capabilities are not the same as a mature, decision-ready program
Organizations often infer maturity from the presence of formal processes, integrated data, documented cost models, and repeatable reporting. These are important capabilities and essential foundations for ITFM. But their presence does not, by itself, demonstrate that a program is creating value when leaders need to make or defend decisions.
The study asked respondents to rate their organization’s overall maturity in managing complex IT financial decisions. It did not independently assess maturity against a defined framework. The results should therefore be understood as a measure of perceived maturity—and compared with what the same respondents said remains unresolved.
That comparison reveals a meaningful disconnect. Can the organization respond to an unexpected question without a lengthy data chase? Can it explain a budget variance before it becomes a surprise? Can it connect a funding request to expected benefit and later show what the investment delivered? Can it identify which dollars can move without disrupting business outcomes?
These are not capabilities that come after maturity. They are part of what a mature ITFM program is expected to deliver.
ITFM maturity should ultimately be judged by the decisions a program improves—not the complexity it maintains
High perceived maturity can coexist with a substantial Value Gap
The disconnect becomes clearest when the same respondents are examined across measures
Respondents are broadly positive about their current ITFM approaches. Sixty-nine percent rate their organization’s maturity in managing complex IT financial decisions at 8 or higher, and 73% rate their likelihood of recommending their current approach at 8 or higher. Yet 68% report five or more unresolved high-priority needs.
These findings are not evidence that established ITFM practices are universally broken. They suggest that organizations may be defining maturity primarily through the tools, processes, models, and reporting capabilities they have put in place—not the full range of decisions those capabilities improve.
Established practices can be broadly recommendable while still leaving multiple high-priority outcomes unresolved
Figure 6: The gap between ITFM capabilities and business outcomes
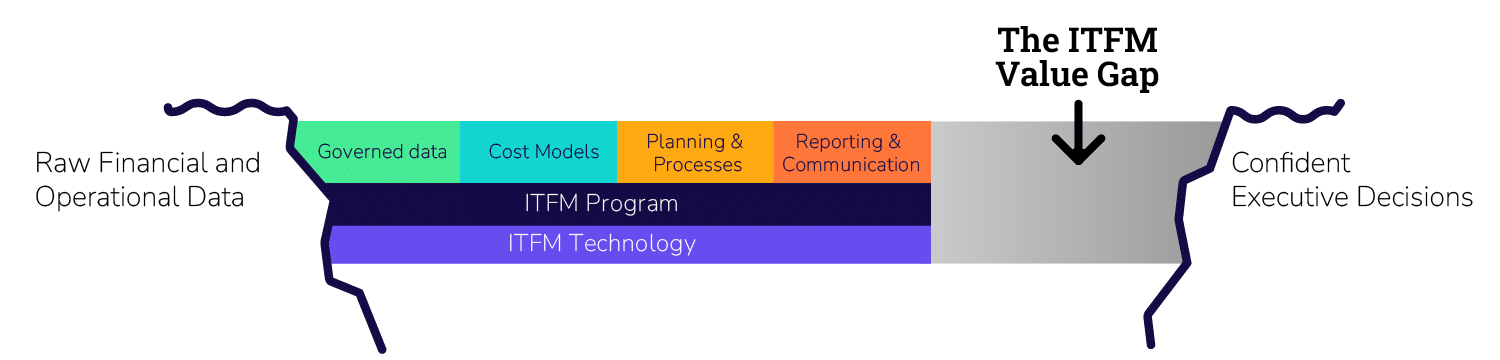
The paradox becomes clearer when the same respondents are examined across measures. Among the 103 leaders who rate their organization’s ITFM maturity at 8 or higher, 94% still report at least one unresolved high-priority need and 55% report five or more. Even among those rating maturity at 9 or higher, 85% report at least one unresolved need. High perceived maturity signals confidence in established capabilities; it does not confirm that the full range of executive decision needs is being addressed.
Scale appears to affect the degree of the Value Gap, but not its presence. Among commercial-platform users, 56% of respondents from organizations spending $50 million to less than $250 million rate their maturity at 8 or higher, compared with 76% of those from organizations spending at least $250 million. Smaller organizations also report a greater density of unresolved needs. Because the smaller subgroup includes only 18 respondents, these comparisons should be treated as directional.
What is more significant is how much remains unresolved at scale. Even among organizations spending at least $250 million annually on technology and using a commercial ITFM platform, 59% report five or more unresolved high-priority needs. The Value Gap therefore cannot be explained by smaller technology budgets or the absence of commercial ITFM investment alone.
The ITFM Value Gap spans multiple capabilities
For most leaders, the gap spans several capabilities–not one isolated feature
Share of respondents with highly important outcomes rated 7 or below on satisfaction
Ninety-six percent report at least one unresolved high-priority need, 86% report three or more, 68% report five or more, and 23% report ten or more. The pattern extends across emerging-spend governance, investment planning, forecasting, reporting, outcome measurement, optimization, and access to executive-ready answers. For most organizations, the Value Gap is not concentrated in one capability or workflow.
That breadth changes the implication of the research. Closing the ITFM Value Gap will not come from adding a single dashboard, report, or isolated automation feature. It requires a program that connects trusted data, business context, financial models, decision workflows, and continuous improvement.
Cost transparency is the foundation, not the destination
A mature ITFM program connects trusted data to decision-ready insight and action
A mature ITFM practice connects three cumulative layers. The Foundation creates credible, defensible, and repeatable information. Communication translates that information into language stakeholders can understand and equips them to use it. Decisions apply that understanding to choices, trade-offs, and action.
Figure 10: The three layers of decision-ready ITFM
| 1. FOUNDATION > | 2. COMMUNICATION > | 3. DECISIONS |
|---|---|---|
|
|
|
The ITFM Value Gap opens when these layers fail to connect—when a credible foundation and effective communication do not consistently translate into better-supported decisions. Cost transparency is essential, but transparency alone does not determine what should happen next.
Programs create less value when they build around the data available rather than the decisions leaders need to make. A technically sophisticated cost model can still miss the mark if it cannot answer the questions that justified the investment. More detail is not automatically more value; the model should be as simple as possible and as detailed as necessary to support defined decisions.
The practical test is straightforward: What changed? Why did it change? What does it mean? What choices or trade-offs are available? What action should follow? What value did the organization receive? ITFM creates executive value when those answers are trusted, timely, connected, and available while the decision can still be influenced.
Senior leaders apply a more demanding standard
The results of the research do not show that more senior respondents are uniformly less satisfied. Instead, seniority changes what leaders consider essential. Compared with VP IT and Technology respondents, CIO, CTO, and SVP leaders place greater importance on governance, model resilience, allocation transparency and adaptability, and direct access to answers without dependence on individual analysts.
CHAPTER 2: AI SPEND IS OUTRUNNING GOVERNANCE
Executive Takeaways
Govern AI as an investment—not simply a new cost line
- Ninety-seven percent of leaders rate AI spend tracking and ROI measurement at 8 or higher in importance, yet only 4% are highly satisfied with their current capabilities. Just 1% are highly satisfied with their taxonomy for emerging spend.
- Establish consistent cost categories, accountable owners, defined use cases and expected outcomes before attempting to prove return. Waiting for perfect attribution risks allowing consumption to outpace financial governance.
AI is creating a new financial management problem
AI is reshaping familiar technology spend and introducing consumption models many organizations are not yet equipped to govern
AI changes the financial management problem in two ways at once. It reshapes familiar software and infrastructure spend while introducing newer usage-based costs, including token consumption and model-inference charges. At the same time, experimentation and purchasing are spreading across the enterprise, creating pressure to demonstrate value before usage and cost patterns are fully understood.
Token consumption may be the most visible new meter, but it is not the full cost of AI. The economic picture can also include compute, storage, data services, platform capacity, and the people required to build and operate AI-enabled workflows. Understanding AI economics therefore requires more than tracking a new line item. It requires connecting technical consumption to the full cost of delivering an AI-enabled service.
For ITFM, this is not primarily an invoice-discovery problem. Leaders need to know who owns the spend, how it should be categorized, which use case or business outcome it supports, how consumption is changing, what future demand may cost, and whether the benefits justify continued investment.
Seeing the spend is only the first step. Governing it means connecting consumption to ownership, future demand, business outcomes, and decisions about where to scale, optimize, change, or stop investment.
Only 4% are highly satisfied with their ability to track AI usage, benefits, costs, and ROI
AI financial governance capabilities rank last on satisfaction
The two AI-related outcomes have the lowest average satisfaction of the outcomes measured in the study. Yet their importance is already clear: 97% of respondents rate each outcome at 8 or higher in importance.
Forty-six percent report limited satisfaction with their ability to categorize and track AI usage, benefits, token consumption costs, and return on AI investment. Another 50% fall into the moderate range. Only 4% are highly satisfied.
The adjacent taxonomy challenge is similarly pronounced. Forty-four percent report limited satisfaction with their ability to establish a taxonomy and cost-category structure for emerging spend, while only 1% are highly satisfied.
These findings expose the ITFM Value Gap in its newest form. AI costs are accumulating, but many organizations lack the financial structure required to govern that spend as a portfolio or demonstrate whether it is creating value.
The market is building a new discipline for AI economics
In August 2026, the Linux Foundation launched the Tokenomics Foundation, backed by 30 initial member organizations, to develop open, vendor-neutral standards, benchmarks, and best practices for understanding the cost and value of AI.
Its roadmap includes shared definitions for AI token economics, a reference model for the full cost of AI, standard methods for measuring cost to serve, frameworks connecting AI investment to business outcomes, improved token-cost telemetry within the FinOps Open Cost and Usage Specification, and practitioner education and certification.
The foundation’s agenda closely mirrors the gaps identified in this study: organizations need a common language for classifying AI spend and a credible way to connect consumption, total cost, and business value. Its formation is another indication that established technology financial-management practices are not yet sufficient for the economics of AI.
— Source: Linux Foundation. Linux Foundation Launches the Tokenomics Foundation to Define the Economics and ROI of AI Value. August 4, 2026.
Before organizations can prove AI value, they need a financial language for AI
The challenge is most acute closest to execution, while scale helps without closing the gap
Return on AI investment is a downstream measure. Before organizations can evaluate it credibly, they must classify AI spend consistently, connect it to accountable owners and defined use cases, track how consumption is changing, and establish which outcomes the investment is expected to produce.
The aggregate findings conceal a pronounced difference by seniority. Among director-level respondents, 94% report limited satisfaction with their ability to categorize and track AI usage, benefits, token costs, and return on investment. That compares with 45% of VP respondents and 25% of CIO, CTO, and SVP respondents.
The same pattern appears in emerging-spend taxonomy. Limited satisfaction rises from 33% among CIO, CTO, and SVP respondents to 40% among VPs and 88% among directors. This suggests that the gap becomes more visible closer to execution, where leaders encounter the practical difficulty of classifying new costs, attributing consumption, and producing answers from incomplete data.
Organizational scale appears to help. Among organizations spending at least $1 billion annually on technology, 31% report limited satisfaction with AI tracking and ROI, compared with 54% of organizations spending between $250 million and $999 million. The corresponding figures for emerging-spend taxonomy are 30% and 54%.
But scale does not solve the problem. Even among the largest organizations, only 9% are highly satisfied with AI tracking and ROI, and only 4% are highly satisfied with emerging-spend taxonomy. The largest organizations appear further ahead, but they have not established a mature answer.
Industry did not materially change the pattern. The measurement and governance challenges surrounding AI appear across sectors rather than being concentrated in industries with a particular technology or regulatory profile.
One emerging practice observed outside this study is AI-specific chargeback: assigning consumption to the business unit, value stream or team that initiated it. This can clarify ownership and place responsibility for defending the spend with its sponsor. But it does not solve forecasting, capture the full cost of an AI-enabled service or demonstrate that the investment produced value. Chargeback establishes accountability; it does not prove return.
Source: Article ‘5 Takeaways from the 2026 ITFMA Conference’
The objective is not perfect attribution on day one. It is a credible and transparent governance structure that can improve as usage patterns, cost models, and business expectations evolve. Waiting for complete data can be as damaging as moving ahead without a shared structure.
The emergence of Tokenomics does not remove AI from the remit of ITFM. It demonstrates that familiar ITFM capabilities must now extend to unfamiliar units of consumption, more variable cost structures, and new approaches to value measurement.
AI therefore creates two agendas for ITFM: governing AI as a category of investment and using AI to improve IT financial decisions. The next chapter examines what leaders expect that AI to deliver.
CHAPTER 3: AI THAT IMPROVES DECISIONS
Executive Takeaways
Use AI to shorten the path from financial change to action
- Leaders prioritize a connected decision agenda: 79% select variance detection and explanation among their three most valuable AI capabilities, 74% select continuous optimization and 62% select automatic forecast updates.
- Ninety-one percent say answering an unplanned spending question without exporting data is highly important, but only 9% are highly satisfied. The opportunity is AI that delivers traceable, decision-ready analysis—not conversational features or faster reporting in isolation.
Leaders want AI to find the signal, explain the driver, and show where action is possible
Faster answers matter, but the greater opportunity is earlier warning, clearer explanation and a shorter path from financial change to action
The survey reveals a practical hierarchy of demand. Senior IT budget leaders most often prioritize AI that helps them interpret financial change, improve the forecast and identify viable opportunities to optimize or redirect spend.
This hierarchy should not be read as diminishing the value of faster reporting or plain-language communication. Both can shorten response times and make analysis easier to use, and the outcome data shows that both remain important and underserved.
AI creates immediate value when it turns one-off requests that once took hours, days or weeks into answers, reports and dashboards delivered in minutes. Its greater strategic opportunity is to move beyond reactive reporting: continuously monitoring financial and operational data, surfacing meaningful changes before leaders ask, connecting those changes to their drivers, quantifying the implications and showing where action is possible.
In this broader role, AI acts as an insight layer over ITFM. It does not replace the financial and operational data, taxonomy, cost models, allocation logic and business context beneath it. It makes those established capabilities easier to interrogate and more useful in the moments when decisions must be made.
Variance, optimization, and forecasting lead the AI agenda
The three most frequently selected AI capabilities form a connected decision agenda: explain where performance is diverging from plan, identify where spending can change, and update the forward view as new actuals arrive.
Seventy-nine percent select detecting and explaining budget variances as one of the three most valuable AI capabilities in an ITFM platform. Seventy-four percent select continuous identification of cost-optimization opportunities, while 62% select automatically updating forecasts as actuals arrive.
The ordering is broadly consistent across seniority levels. CIO, CTO, SVP, VP, and director respondents all place variance detection, optimization, and forecasting among their leading priorities. AI’s perceived value is therefore not confined to an individual persona or level of the organization.
Together, the top three choices describe an AI layer focused on continuous financial management rather than periodic reporting.
For variance management, identifying that spending is above plan is not enough. Decision-ready analysis should explain what changed, identify the underlying cost or consumption drivers, show which services or business areas are affected, and quantify the potential full-year impact. A variance explanation that simply restates the existence of overspend is faster reporting, not better insight.
For forecasting, AI creates the opportunity to incorporate actuals continuously, detect when previous assumptions are no longer holding, and flag budget risk before the organization reaches the end of the reporting period. It can also help leaders explore the financial implications of changing consumption, pricing, adoption, or investment assumptions without rebuilding a model for every scenario.
For optimization, the opportunity extends beyond identifying the largest line items. AI can help surface underused resources, duplicative costs, unusual consumption patterns, and areas where spending may be reducible or deferrable. But a theoretical opportunity is not automatically realizable savings. Contractual commitments, technology dependencies, implementation effort, operational risk, and business impact still determine whether action is feasible.
One-third of respondents also selected automated detection of reconciliation or data-quality issues before they reach stakeholders. This is not separate from decision support. Anomalies can exist in the underlying data as well as in financial performance, and AI that detects both can prevent a misleading answer from reaching leadership.
Only 8% selected automatic governance and tracking of AI-related spend as a top-three AI platform capability. That does not contradict the governance challenge examined in Chapter 2. It suggests that leaders see governing AI spend as a financial-management requirement, while prioritizing the use of AI itself for variance analysis, optimization, and forecasting.
Conversational AI may be more important than its feature ranking suggests
The survey’s AI rankings and outcome ratings answer different questions
At first glance, the findings appear to pull in different directions. When asked to select no more than three AI capabilities, 23% of respondents choose natural-language question answering and 18% choose AI-generated plain-language narratives. Yet in separate outcome ratings, 91% say answering an unplanned question about IT spending without exporting data is highly important, and 69% say the same about producing a plain-language narrative for non-technical leaders.
The difference lies in what each question measures. The AI question forced respondents to prioritize three capabilities from a broader list. The outcome question measures how important each result is independently, regardless of how it is delivered. The lower AI selections therefore reflect relative priority among competing uses of AI—not a lack of demand for rapid answers or plain-language communication.
A leader can prioritize variance analysis, optimization and forecasting as uses of AI while still regarding answers and narratives as essential. Those analytical capabilities can provide the evidence and explanation that a conversational experience, report or dashboard ultimately communicates. The survey also presented short capability descriptions rather than a complete workflow connecting analysis, exploration and communication.
The satisfaction results make the opportunity clearer. Only 9% are highly satisfied with their current ability to answer an unplanned spending question without exporting data, and only 5% are highly satisfied with producing plain-language narratives for non-technical leaders.
Executive communication outcomes remain important and underserved
The chart shows a substantial gap across every executive communication outcome measured. Between 89% and 91% of respondents rate translating IT costs into business terms, producing leadership-ready reports, and answering unplanned questions without exporting data as highly important. Yet only 9% to 15% are highly satisfied with their current ability to deliver these outcomes. Plain-language narratives show a similarly wide gap: 69% rate them as highly important, while only 5% are highly satisfied.
For the most senior leaders, the need is even more pronounced. Eighty-one percent of C-level and SVP respondents rate plain-language narratives as highly important, compared with 68% of VPs and 47% of directors. Yet only 6% of the C-level and SVP group are highly satisfied. The broader executive communication gap remains consistent across industries and IT-budget bands.
Conversational AI can help close this gap by reducing the time and specialist intervention required to move from a financial question to a decision-ready answer. A leader might ask why spending has moved away from plan, inspect the drivers and assumptions, explore the forecast impact, identify possible actions, and generate the narrative and visual evidence needed for an executive conversation. Its value lies in connecting variance analysis, forecasting, optimization, and reporting in one traceable experience grounded in governed ITFM data, with assumptions and sources visible.
CHAPTER 4: FUNDING IS NOT THE FINISH LINE
Executive Takeaways
Make funding the start of accountability—not the end
- Ninety percent of leaders say determining whether technology investments delivered their promised outcomes is highly important, but only 13% are highly satisfied with their current ability to do so.
- Define expected benefits when funding is approved, track results through delivery and use that evidence to inform the next allocation decision. Optimization creates strategic value when it releases resources for higher-priority outcomes—not simply when it reduces cost.
From cost reporting to outcome accountability
Once funding is approved, organizations still need to track whether the investment delivers the benefits used to justify it
Traditional ITFM is strong at explaining where money went. The next era must also explain what the organization expected to achieve, whether the investment is producing those results, and how new evidence should influence future funding decisions.
Funding approval should establish accountability, not end it. Expected revenue, savings, risk reduction, productivity, service improvement, or strategic benefit should be defined when an initiative is proposed, tracked as the work progresses, and revisited as costs, assumptions, and results change.
Just 1 of 104 leaders prioritizing all three outcomes is highly satisfied with all three.
Source: Nicus 2026 IT Financial Decision-Making Study. Base: respondents rating all three lifecycle outcomes highly important (n=104).
The largest value gaps appear before and after the funding decision
The gaps span the full investment lifecycle. Leaders need to model the impact of a proposed change, define the benefit expected when funding is approved, and later determine whether the investment delivered what the original case promised. Weakness at any stage makes the next decision less informed.
The disconnect appears most pronounced closest to execution. Directionally, 94% of director-level respondents have an unresolved high-priority need around documenting expected benefits, 88% around determining whether investments delivered promised outcomes, and 82% around modeling proposed changes. This suggests that the investment lifecycle may appear more connected from the top than it feels to those operating it.
Connecting cost, expected value, realized results, and business context allows ITFM to become a mechanism for portfolio learning. Leaders can compare investments more consistently, challenge assumptions earlier, and use what they learn to strengthen the next allocation decision.
Cost without outcome is incomplete. Outcome without cost is ungoverned.
Optimization is not simply cost reduction
Cost optimization is often framed as an episodic reduction exercise. The survey points toward a more strategic job: continuously identifying spend that can be reduced, deferred, renegotiated, retired, or redirected without disrupting the business results technology is expected to support.
Not every reduction creates equal value. A dollar removed indiscriminately may increase risk, constrain capacity, or delay an important outcome. A dollar released through better utilization insight, portfolio comparison, or scenario modeling can be redirected toward higher-priority work. Optimization therefore creates value not only by lowering cost, but by increasing the organization’s freedom to invest.
That helps explain why 74% of respondents select continuous identification of cost-optimization opportunities as one of their three most valuable AI capabilities. Leaders are not simply asking AI to produce a longer list of costs. They want it to help identify viable opportunities, expose the implications, and show where action may be possible.
AI can expand the field of opportunities, but it cannot make the allocation decision independently. Recommendations create value when their assumptions are explainable, their effect on business outcomes is understood, ownership is clear, and empowered stakeholders can act.
CHAPTER 5: THE DECISION WINDOW IS SHRINKING
Executive Takeaways
Forecast while there is still time to act
- Seventy-eight percent of leaders rate both timely variance insight and an updated full-year forecast as highly important, but only 5% are highly satisfied with both.
- Shift the emphasis from periodically producing a more accurate number to detecting material change, refreshing assumptions and showing available options while leaders can still influence the outcome.
Forecasting for a more volatile technology cost base
Annual planning assumptions are increasingly challenged by variable consumption, pricing changes, and rapid technology adoption
Forecasting has always required judgment. The difficulty increases when the cost base changes faster than the planning cadence. Cloud consumption, vendor pricing, workforce costs, AI usage, organizational restructuring, and shifting investment priorities can make a point-in-time forecast obsolete before the organization reaches its next formal planning cycle.
The next era of ITFM requires a tighter connection between actuals, operational drivers, assumptions, and scenarios. Leaders need to understand not only where the current forecast lands, but what changed it, which assumptions are no longer holding, what range of outcomes is plausible, and what intervention remains available.
78% of respondents rate both timely variance insight and an updated full-year forecast as highly important. Only 5% are highly satisfied with both.
Source: Nicus 2026 IT Financial Decision-Making Study. Base: respondents rating both outcomes highly important (n=117).
Leaders need earlier signals, more current forecasts, and fewer surprises
The chart shows a wide gap between the importance of timely forecasting outcomes and leaders’ satisfaction with their current ability to achieve them. Reducing the time required to identify budget variances and producing an updated full-year forecast from actuals are each highly important to 87% of respondents. Yet only 11% and 18%, respectively, are highly satisfied. Reducing defensive over-forecasting is highly important to 75%, while only 8% are highly satisfied.
Together, these findings point to a forecasting problem that extends beyond producing a more accurate number. Leaders need earlier evidence that performance is moving away from plan, a current view of where the year is likely to land, and enough confidence in the process to act without creating new budget risk.
The finding on defensive over-forecasting adds a behavioral dimension. Budget holders may preserve contingency because releasing funds can weaken their ability to respond later or reduce future allocations. Better visibility alone may not change that behavior. Organizations also need transparent assumptions and governance that allow capacity to be released without automatically penalizing the budget owner.
Seniority changes how strongly this issue is perceived. Eighty-three percent of C-level and SVP respondents rate reducing defensive over-forecasting as highly important, compared with 76% of VPs and 47% of directors. The difference suggests that senior leaders are more likely to see the aggregate effect: precautionary buffers held across multiple budgets can prevent capital from moving to higher-priority needs.
Continuous forecasting extends planning beyond the annual budget cycle
The large gaps in faster variance detection and updated full-year forecasting point to a broader issue: a forecast has limited decision value if it becomes accurate only after the relevant funding, resource, or remediation decision has been made.
In a more mature planning approach, forecasting is not an activity reserved for the annual budget cycle. Organizations continuously maintain a multi-year view, with actuals, commitments, operational signals, and changing assumptions informing the outlook throughout the year. Annual budgeting remains an important governance milestone, but it becomes another update to an already-current forecast rather than a once-a-year rebuild.
Continuous forecasting does not mean constantly rebuilding every line item. It means detecting material change earlier, updating the assumptions and forecasts affected by it, and giving leaders a current view while options are still available.
AI can make this approach more practical by monitoring for meaningful deviations, identifying their drivers, showing which assumptions have changed, and helping teams assess the potential forecast impact. Human judgment remains essential, but it becomes more useful when the evidence arrives in time to influence the decision.
CHAPTER 6: THE PLATFORM MUST DO MORE OF THE WORK
Executive Takeaways
Choose the platform and provider that accelerate decision value
- Commercial software helps, but adoption alone does not create decision readiness: 63% of commercial-platform users—and 51% of commercial-platform users at organizations spending at least $1 billion annually on IT—still report five or more unresolved high-priority needs.
- Evaluate the decisions the platform enables, whether its financial models reflect how the organization makes those decisions, how much work remains outside the software, and the expertise, methodologies, and proven outcomes the provider brings. Ask providers to demonstrate the complete path from source data to a traceable, decision-ready answer—not simply a list of features.
ITFM value should not depend on enterprise-scale resources
As ITFM complexity grows, a purpose-built platform becomes essential—but it must deliver more than financial control
Spreadsheets and ERP systems can support IT budgeting and basic cost reporting. But as data sources multiply, consumption-based spending expands, allocation models become more complex, and leaders require more frequent and granular answers, general-purpose tools become increasingly difficult to sustain.
The tipping point is not determined by budget alone. It arrives when the combination of scale, model complexity, reporting frequency, and stakeholder demand makes it impractical to produce timely, repeatable, and defensible analysis without a purpose-built ITFM platform.
The research examines organizations that have already crossed that threshold: every respondent uses either a commercial ITFM platform or a homegrown solution. Their experience shows that the platform matters—but also that adopting one does not, by itself, create a decision-ready ITFM capability.
The next question is how much work must still happen around the platform before financial data can support a trusted decision.
A purpose-built platform becomes essential as complexity grows. Its value depends on how effectively it turns that complexity into better decisions.
Commercial platforms reduce strain—but do not close the gap
The clearest platform-level distinction in the research is between commercial ITFM platforms and homegrown or internally developed approaches.
Every respondent using a homegrown approach reports five or more unresolved high-priority needs, compared with 63% of commercial-platform users. Homegrown users also report lower confidence in their approach: 43% rate their maturity at 8-10 and 48% rate their likelihood of recommending it at 8-10, compared with 73% and 78% of commercial-platform users, respectively.
The survey cannot establish that platform choice caused these differences. Organizations using internal solutions may differ in complexity, resourcing, investment, or stage of maturity, and the homegrown subgroup is relatively small.
Nevertheless, the strength of the pattern suggests that internal solutions may come under greater strain as ITFM requirements extend beyond reporting and allocation into forecasting, emerging-spend governance, optimization, and executive decision support.
The commercial-platform result is equally important. Nearly two-thirds of those users still report five or more unresolved high-priority needs. Commercial-platform users report a narrower Value Gap, but substantial work remains.
Commercial platforms are associated with less strain—but substantial decision work remains
Scale is compensating for what platforms do not provide
The prevalence of unresolved needs declines as organizational IT spend increases. Eighty-nine percent of respondents from organizations spending between $50 million and $249 million annually on IT report five or more unresolved high-priority needs. This falls to 73% among organizations spending between $250 million and $999 million, and 54% among those spending at least $1 billion.
The pattern becomes more revealing when considered alongside platform adoption. Every respondent in the $50 million to $249 million group uses a commercial platform, yet 89% still report five or more unresolved needs.
Among organizations spending at least $250 million and using a commercial platform, 59% report five or more unresolved needs. Even among commercial-platform users from organizations spending at least $1 billion on IT, 51% report five or more.
The research cannot determine why larger organizations report fewer unresolved needs. They may have more specialized teams, stronger governance, greater executive sponsorship, more mature processes, or greater access to implementation and consulting resources.
The practical implication is that scale may help organizations compensate for capabilities that current platforms do not fully provide. Smaller organizations can acquire commercial software but may have less capacity to assemble and maintain the expertise surrounding it.
Flexibility and expertise shape platform value
Leaders place greater importance on the ability to adapt and the quality of provider support than on total cost of ownership
Once core platform requirements are met, the selection question becomes how effectively the software can adapt to the organization and how much expertise the provider brings to making it successful. Seventy-eight percent of respondents rate configuration flexibility as highly important, while 75% say the same about the quality of consultation, services, and ongoing support. Total cost of ownership ranks lower at 67%.
Flexibility should not mean endless customization. It means being able to adapt data structures, cost models, allocation logic, and outputs as the organization, its technology portfolio, and its decision priorities change. Without that flexibility, teams may be forced to fit decisions into the platform’s existing structure or perform more of the work outside it.
A standard taxonomy can accelerate implementation, but it should not constrain how the organization understands its costs. The financial model must be able to connect spending to the services, investments, business capabilities, and outcomes that leaders use to make decisions.
Expertise is the other half of the equation. Flexible software does not tell an organization how to structure its model, define meaningful outcomes, or apply financial information to a decision. The provider’s experience and methodologies help translate flexibility into a working ITFM capability. Over time, more of that repeatable expertise should be codified within the platform so that specialist knowledge can focus on business trade-offs and outcomes.
The lower ranking for total cost of ownership does not make economics unimportant. It suggests that cost should be evaluated in the context of time to value, internal resource demands, and the decisions the combined platform and provider can enable.
Ask the provider to demonstrate a decision—not just the software
Start with a decision your organization actually faces. Ask the provider to show how the financial model supports it, how the analysis adapts when an assumption or structure changes, and how the resulting answer traces back to its data and logic. Make explicit what the platform performs, what requires provider services, and what remains with the internal team. Then ask for evidence of outcomes in organizations with comparable complexity.
Too much decision work still happens around the platform
The outcome data provides a clearer view of what leaders need platforms and the surrounding ITFM practice to accomplish
Leaders want to model change within their primary ITFM environment, adapt financial structures as decisions change, produce leadership-ready analysis without extensive manual intervention, connect investments to promised outcomes, and protect knowledge about how cost models work.
Across each of these areas, high satisfaction remains rare.
These are not simply requests for additional reporting features. Together, they point to the work required to keep financial models relevant, respond to change, preserve trust, and turn analysis into evidence that leaders can use.
Much of that work currently sits outside the platform—in data preparation, model development, specialist knowledge, manual analysis, and services-led implementation. This helps explain why a commercial platform can coexist with multiple unresolved needs and why organizations with greater scale appear better able to compensate.
The platform must shorten the distance from data to decision
The opportunity for the next generation of ITFM platforms is to reduce how much expertise and manual effort organizations must assemble before the software produces decision value.
This does not mean replacing ITFM expertise or organizational judgment. It means allowing that expertise to focus on investment choices, business implications, and outcomes rather than being repeatedly consumed by preparing data, maintaining models, validating analysis, and formatting results.
AI can accelerate this shift. The capabilities leaders prioritize are closely connected to the financial-management process:
These priorities suggest that leaders value AI when it helps move from changing data to a clear implication or action. Within a governed ITFM environment, AI can reduce manual analytical work, surface significant changes earlier, and help make financial reasoning available when decisions are being made.
The objective is not automation for its own sake. It is to shorten the time between a change in the financial picture and a trusted decision—while keeping the underlying data, assumptions, and reasoning traceable.
CONCLUSION
Closing the ITFM Value Gap
The research does not describe a discipline that has failed. Organizations have made substantial progress in establishing financial control, cost transparency, repeatable processes, and confidence in their ITFM approaches.
But established capability is not the same as completed maturity. Sixty-nine percent of respondents rate their maturity at 8 or higher and 73% would recommend their current approach, yet 68% still report five or more unresolved high-priority needs. The ITFM Value Gap exists between the capabilities organizations have established and the value those capabilities create when leaders must make, defend, and revisit technology investment decisions.
Closing that gap requires ITFM to build on its financial foundation. Leaders still need credible data, defensible cost models, disciplined planning, and transparent reporting. Increasingly, however, they also need to understand why results changed, evaluate competing investments, connect funding to expected outcomes, identify resources that can be redirected, and answer unexpected questions before the opportunity to act has passed.
AI intensifies both sides of this challenge. As a rapidly expanding category of spend, it introduces unfamiliar consumption models, limited forecasting history, distributed ownership, and growing pressure to demonstrate value. As an ITFM capability, AI can help explain variances, update forecasts, identify optimization opportunities, and translate financial information into decision-ready evidence. Its value will depend on whether those outputs remain grounded in governed data, visible assumptions, and traceable financial logic.
Platforms must also carry more of the burden. Purpose-built ITFM software becomes essential as financial and operational complexity grows, but adopting a platform does not automatically create decision value. The next opportunity is to reduce how much manual effort and specialist intervention must occur between financial data and a trusted answer—allowing ITFM expertise to focus more fully on business implications, trade-offs, and action.
The resulting mandate is broader than reporting where technology money went. ITFM must help the organization decide what to fund, what to change, what to stop, and whether previous investments delivered what was promised. It must move from periodic visibility toward continuous decision support without sacrificing financial rigor or human accountability.
That is how the ITFM Value Gap closes: not when an organization produces more information, but when that information consistently leads to faster, clearer, and more defensible decisions.
ITFM earns its value at the moment a better decision is made.
Six questions that expose the ITFM Value Gap
A decision-ready ITFM program should enable senior leaders to answer yes to each of these questions.
- Can we answer an unexpected question about technology spending in time to influence the decision?
- Can we explain a material variance, its underlying drivers, its forecast impact, and the actions available?
- Can we connect each major technology investment to an accountable owner, its expected outcome, its current cost, and evidence of realized value?
- Can we identify spending that can be reduced, deferred, or redirected—and understand the effect on business outcomes?
- Can we govern AI and other emerging spend from consumption and ownership through forecasting and value measurement?
- Does our ITFM platform reduce dependence on manual data preparation, specialist model-building, and individual analysts as complexity grows?
Every “not yet” identifies a gap between established ITFM capability and the decision value it creates—and a place to focus next.
RESEARCH METHODOLOGY
About the 2026 IT Financial Decision-Making Study
Nicus commissioned a third-party research agency to source and survey 150 qualified senior IT and technology budget leaders in North America. The research was fielded from June 11 through July 29, 2026.
Sample and qualification
Respondents were employed full time, worked at organizations with at least $50 million in annual IT spend, and were personally accountable for governing and defending a technology budget to senior leadership, the C-suite, or the board. The sample intentionally emphasizes large organizations with established ITFM approaches. Additional details about respondent seniority, budget responsibility, organizational IT spend, industry and platform use appear in the Research Profile.
Research design
The study used an importance–satisfaction research design based on Importance–Performance Analysis. Respondents rated the importance of 20 IT financial decision-making outcomes and their satisfaction with how well current tools and processes accomplish each outcome. Both measures used 10-point scales.
The outcome statements were framed using Jobs to be Done principles, focusing on what leaders need to accomplish rather than their satisfaction with individual product features. Jobs to be Done shaped what the study measured; importance–satisfaction analysis shaped how those outcomes were evaluated.
Respondents also rated their organization’s maturity in managing complex IT financial decisions, their likelihood of recommending their current approach, platform-selection criteria and the value of potential AI capabilities. Maturity and satisfaction are respondent-reported measures and were not independently assessed against a defined maturity framework.
How to interpret the findings
The study asks a different question from a conventional satisfaction survey: which outcomes matter most, and where does meaningful room for improvement remain? For readability, the report presents response distributions and top-two-box percentages rather than mean scores or a traditional four-quadrant Importance–Performance Analysis.
| Highly important | Importance rating of 9 or 10 |
| Limited satisfaction | Satisfaction rating of 1 through 6 |
| Moderate satisfaction | Satisfaction rating of 7 or 8 |
| Highly satisfied | Satisfaction rating of 9 or 10 |
| Unresolved high-priority need | An outcome rated 9 or 10 in importance and 7 or below in satisfaction |
The unresolved-need definition is deliberately conservative. A satisfaction rating of 8 is treated as a strong result rather than an unresolved need.
Reporting conventions
Unless otherwise stated, findings use a base of all 150 qualified respondents. Percentages are rounded and may not total 100%. Multiple-response questions may total more than 100%. For questions concerning the value of potential AI capabilities, respondents could select up to three responses.
Subgroup comparisons are directional, particularly where the respondent base is smaller. Associations between characteristics such as organizational scale, seniority or platform use and reported outcomes do not establish causation.
ITFM Value Gap
The report uses the term ITFM Value Gap to describe the distance between the capabilities an organization has established and the value its ITFM program creates through better decisions and outcomes. The ITFM Value Gap is an organizing interpretation of the research findings. It is not a separately calculated index, survey score or simple numerical difference between importance and satisfaction.
Interpretation
The findings represent the qualified respondents and should be interpreted as directional insight into senior IT budget leaders rather than a population estimate for all organizations. The research does not independently validate respondents’ assessments of organizational maturity, satisfaction or program performance. Overall satisfaction and opportunity patterns were broadly consistent across the major industries represented, but industry and subgroup findings should not be interpreted as definitive estimates beyond the study sample.
ABOUT NICUS
Financial Intelligence for Smarter Tech Decisions
Nicus brings clarity, control, and confidence to technology investment. Its IT Financial Management platform connects financial and operational data, supports planning and forecasting, identifies optimization opportunities, and helps organizations connect technology spend to business priorities and outcomes.
Through AI-powered insights that leaders can understand, explain, defend, and act on, Nicus helps IT, finance, and business teams move from reporting what happened to deciding what to do next.
The Nicus ITFM Value Framework provides a structured way to identify the decisions an ITFM program must improve, connect technology investments to expected outcomes, and measure whether value is being realized. It helps organizations focus their software, data, financial models, processes, and expertise on the business decisions that matter most.
Clarity. Control. Confidence.
Where is your ITFM Value Gap?
Start with a Nicus ITFM Value Assessment. Identify the decisions your current program needs to support, the capabilities standing in the way, and the highest-value opportunities to improve.